Milton, GA & North Fulton
Business Succession Planning in Milton, GA
The Milton version of succession usually involves a company, a piece of land, and more than one child. The son has run the building company’s crews for ten years. The daughter is a physician in Roswell and has no interest in the business but grew up on the farm. The general manager who has been there since the second truck would buy in tomorrow if he could find the money. The owner knows roughly what should happen. What nobody has worked out is how the successor pays, what the other children receive, and what happens to the plan if the owner is not around to finish it.
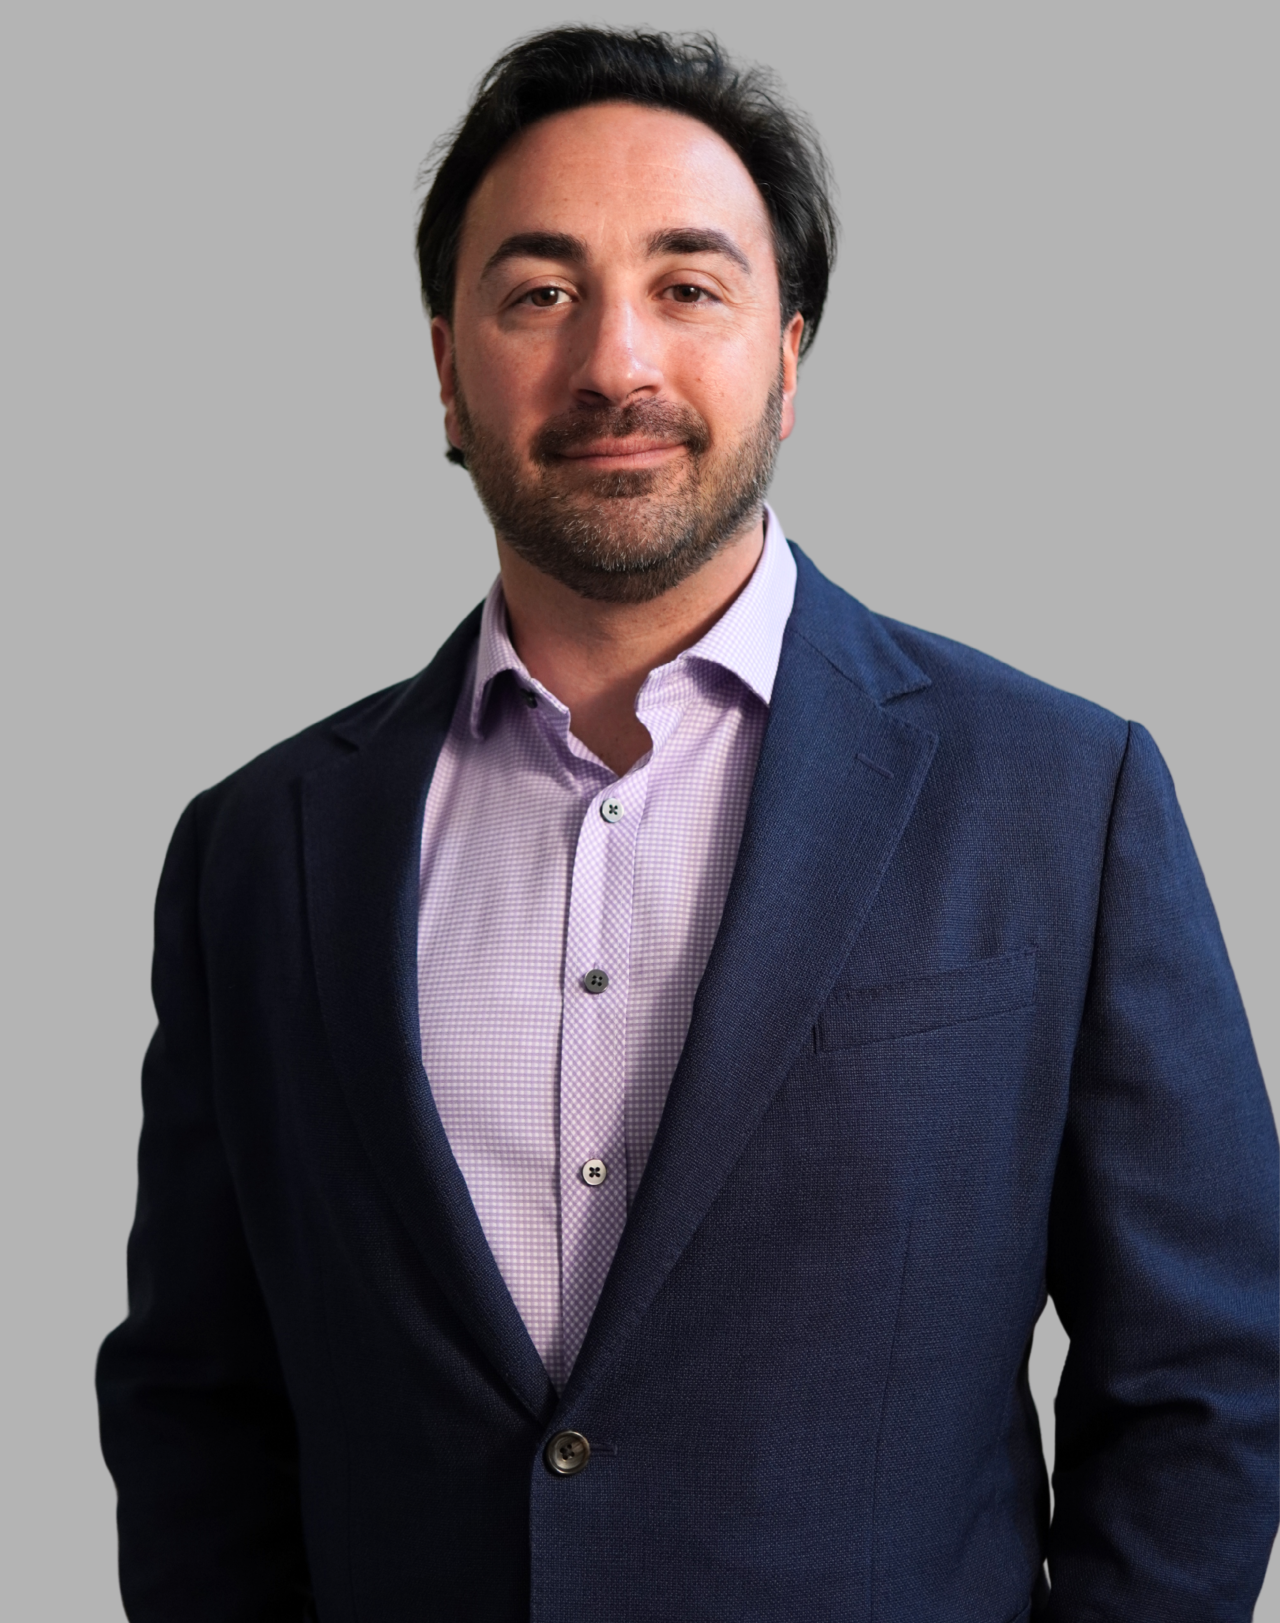
Cinder Wealth is based in Cumming, a short drive north of Milton up Highway 9, and works with Milton and North Fulton owners on transfers to family, partners, and key employees. Matt Losanno models the transfer from both sides: what the seller needs it to produce, and how the successor funds it without breaking the company. Cinder does not draft the agreements or set the valuation. Matt builds the financial plan around them and keeps the attorney, the CPA, and the valuation professional working from the same assumptions.
The Milton Succession Picture
The business goes to one child. The land is worth more. Now what is fair?
Milton has 1,774 residents who run their own incorporated company, a median household income of $171,295, and some of the largest residential parcels in the Atlanta metro. Many of those companies were built over decades by a founder whose home and acreage have appreciated as much as the business, and whose children have gone in different directions. One is in the company. One is not. The property is often the largest single asset, and it does not divide neatly.
An internal transfer also has to be paid for out of the business. A child or a manager rarely has the cash to buy a company outright, so the founder becomes the lender, stays involved longer than intended, and depends on the successor’s management for retirement income. That can work well. It works far better when it is designed years ahead rather than assembled the year the founder wants out.
1,774
Milton residents self-employed in their own incorporated business, U.S. Census Bureau
$171,295
Median household income in Milton, 2020 through 2024, U.S. Census Bureau
41,296
Milton population, 2020 Census, U.S. Census Bureau
Local
Cinder Wealth is based in Cumming and works with owners across North Fulton
Who Matt Works With
Milton owners passing the company to someone already inside it
Cinder Wealth’s succession clients typically own companies producing $500,000 or more in annual profit and intend to transfer to a child, a partner, or a key employee rather than sell to an outside buyer.
Five or more years of lead time is where the work pays off, because a staged buy-in, the seller’s retirement income, the estate plan for the children outside the business, and the documents that protect everyone take that long to put in place.

Family Trade and Service Companies
Building, landscape, equipment, and specialty trade businesses that serve the estate properties, where a son or daughter runs operations and the founder is ready to step back but not to give the company away.
Families With a Business and Significant Land
Owners whose estate includes both a company and acreage, where treating the children fairly means deciding what each receives, when, and how the values are balanced.
Professional Firms With a Partner Track
Engineering, consulting, accounting, and law firms in Alpharetta and along GA-400 where a senior partner is retiring and the remaining partners need a funded, agreed way to buy the departing interest.
Owners Selling to a General Manager
Owners of route, service, and franchise businesses transferring to the person who has effectively run the company for years but cannot write the check to buy it.
Multi-Owner Companies With an Old Buy-Sell
Businesses with two or more owners whose agreement was drafted at formation and no longer matches the value, the ownership split, or the insurance that was supposed to fund a buyout.
Succession Planning Areas
What Matt works through with Milton owners and successors
The Seller’s Side
Whether the Founder Can Afford to Step Back
Because an internal transfer is paid over years rather than at a closing, the founder’s retirement rides on how the company performs under new management. Matt projects the household’s income under the proposed terms, including a version where the payments slow down, so the owner can see whether the plan holds before signing anything.
The Buyer’s Side
How the Successor Pays
A seller note, bank financing, a reduced salary, and a share of future profit are the usual ingredients, in some combination. Matt tests whether the company can carry the debt and still pay the successor enough to live on. The CPA and the lender confirm the structure.
Staged Transfers
Ownership in Steps Rather Than All at Once
Transferring a percentage every few years sets the price, the timeline, and the change in compensation at each step. Done well, it protects the founder’s retirement and keeps the successor from being stuck in a deal that does not pay. Matt runs the numbers for both parties. The attorney drafts the agreement and the valuation professional sets the price.
Valuation
A Price Both Sides and the IRS Accept
A transfer to a child or an employee needs a figure that holds up on audit, that the buyer can actually pay, and that the seller can retire on. Cinder does not perform valuations. Matt explains what the number means for each side and works with the valuation professional and the CPA.
Buy-Sell Agreements
The Document Nobody Has Read Since Signing
Most multi-owner Milton companies have a buy-sell agreement, and most were signed when the business was worth a fraction of today’s value. Matt reviews the triggers, the valuation method, and the funding with the owners so the attorney can update the document to match the company that exists now.
Funding the Agreement
What Happens on the Worst Day
A buy-sell that obligates the surviving owners to purchase a deceased partner’s share is worth exactly what they can pay. Life and disability buyout coverage, a cash reserve, and an installment structure each cost something and are taxed differently. Matt compares them. Advisors may earn commissions on some insurance products, and Matt will say so before anything is put in place.
Family Fairness
The Company, the Land, and the Children Outside Both
When one child runs the business and the others do not, an equal split hands control to people who are not in it. Milton families often have acreage and a home to balance with, alongside life insurance or other assets. Matt models the options for treating everyone fairly. The estate attorney drafts the documents.
Taxes and Estate
Gift, Sale, or a Mix of Both
Passing ownership by gift, by sale, or partly each way changes the income tax, gift tax, and basis outcome for the whole family. Matt gets those options to the CPA and the estate attorney with time to use them and keeps the household plan current as the transfer moves forward.
Why Internal Transfers Are Harder
Handing the company to family is not the easy option
An outside buyer shows up with financing and a closing date. A successor inside the business shows up with ability and no money, and the founder becomes the lender, the mentor, and the retiree at once.
The buyer almost never has the cash
A child or a manager rarely has the funds to buy a profitable company outright. The purchase is financed by the seller, a lender, or the business itself over years, and the founder’s retirement income depends on how well that financing holds.
An unfunded buy-sell is a promise, not a plan
An agreement that requires a buyout with no insurance, reserve, or financing behind it leaves the surviving owners choosing between draining the company and negotiating with a grieving family. Funding is what makes the document work.
Running the company and owning it change hands on different dates
A successor can manage the business long before owning it, and own most of it while the founder still decides. Writing down what transfers when, and what the founder’s role and pay look like at each stage, prevents the most common disputes.
Family businesses answer to more than two people
Spouses, siblings outside the company, and children who expected equal treatment all have a view, and in Milton the land is often part of the argument. A plan that works only for the two people signing it rarely survives the first family meeting.
Based in Cumming
A local advisor for Milton owners planning a handover
Cinder Wealth Advisors is based in Cumming, a short drive north of Milton up Highway 9, and serves business owners across Milton, Alpharetta, Roswell, Canton, and the rest of North Fulton. Matt Losanno founded the firm after meeting too many owners whose CPA, attorney, and broker had never once been in the same room.
Succession is where that matters most, because every piece leans on another. The price drives the founder’s retirement, the financing drives the successor’s pay, and the estate plan drives what the children outside the company receive. Matt holds all of it in one model and keeps the attorney, the CPA, and the valuation professional on the same assumptions. The first meeting is usually about who the successor is and how far along the plan really is.
Cinder Wealth is a fee-based advisory firm. Advisors may earn commissions on some insurance products.
Common Questions
Succession questions from Milton owners
Straight answers about family transfers, employee buy-ins, buy-sell agreements, and where Cinder fits next to the attorney and the CPA.
Is succession planning the same as selling the business?
Not quite. A sale to an outside buyer is paid at closing and the owner leaves. A succession transfers the company to someone already connected to it, is usually financed over time, and keeps the owner involved through the handover. The money questions overlap, but the funding, the timeline, and the family dynamics differ.
My child runs the company but cannot afford to buy it. Is that unusual?
It is the normal case. Almost no internal successor has the cash to buy a profitable business outright. The purchase is financed by the seller, a lender, or the company over several years, and the planning question is whether the business can carry that while paying the successor a living and the founder a retirement.
How do we set a price for a transfer to family?
With a valuation professional, because the IRS treats a bargain sale to a child as a partial gift. Cinder does not perform valuations. Matt helps the family understand what the number means for the founder’s retirement and the child’s ability to pay, and coordinates with the valuation professional, the CPA, and the estate attorney.
One child gets the business. What do the others get?
Usually something other than shares in a company they do not work in. Many Milton families balance the estate with the land, the home, other assets, or life insurance so that the child in the business controls it and the others are treated fairly. Matt models the options. The estate attorney drafts the plan.
Our buy-sell agreement is from when we started. Does it still hold up?
Probably not without a review. Most were signed when the company was worth far less, and many use a fixed price or a formula that no longer fits. The triggers, the valuation method, and the funding all deserve a fresh look so the attorney can update the document.
How far ahead should a Milton owner start?
Five years or more before the intended handover. A staged buy-in, a seller note, the successor’s development, and the estate and insurance planning that protect everyone all take that long to arrange properly. Starting later is possible, but with fewer choices and more risk.
Should I keep working after the transfer?
Many founders do, for a defined period and a defined role, and it often helps the successor and the customers. The terms should be written down: how long, what authority, what pay, and when it ends. Matt models the founder’s income under the arrangement. The attorney puts it in the agreement.
What if the successor backs out partway through?
It happens, so the plan should allow for it. A staged transfer, a clear agreement on shares already purchased, and a company that remains sellable to an outside buyer all protect the founder if the internal transfer stalls. The attorney builds those terms in. Matt keeps the financial plan workable under either outcome.
Talk to Matt
Find out whether the handover you have in mind can be funded
If you own a Milton company and already know who should take it over, start with a conversation about the timeline, the price, and how both sides of the transfer get paid.
Related Pages
The information presented on this page is for educational purposes only and does not constitute personalized financial, tax, or legal advice. Cinder Wealth is not a licensed tax professional, does not draft legal documents, and does not perform business valuations. All strategies discussed should be evaluated with your own CPA, attorney, and qualified financial advisor before implementation. All investing involves risk, including the possible loss of principal. Investment Advisory Services are offered through Csenge Advisory Group, LLC, a registered investment advisor. Cinder Wealth Advisors is not affiliated with Csenge Advisory Group, LLC.